
Types of GST in India (CGST, SGST, IGST & UTGST) Explained | 2025 Guide
Introduction
If you’ve ever stared at an invoice wondering why there are two 9% lines on one bill and one 18% line on another welcome to the club. For many businesses, the different types of GST in India feel like alphabet soup: CGST SGST IGST (and yes, UTGST too). The result? Mis-charged taxes, blocked ITC, irate customers, and compliance headaches you didn’t budget for.
Problem (relatable, real-world):
- You sell within your state and charge CGST + SGST—great. Then a courier sends the package across state lines and suddenly it should’ve been IGST. Oops.
- You try to set off SGST credit against CGST liability because “credit is credit,” right? Not quite.
- You operate in a Union Territory and don’t know if it’s SGST or UTGST.
- Marketplaces and cross-border orders add a whole new layer of “wait, what applies here?”
This guide de-jargonizes Goods and Services Tax (GST)—India’s unified, destination-based indirect tax—so you can quickly decide which tax applies, how much to charge, and how to claim credit correctly (without playing trial-and-error with your returns).
What is GST in India?
Before we dive into the types, let’s get the basics right: What is GST?
GST, or Goods and Services Tax, is India’s destination-based tax on the supply of goods and services. In simple terms, it’s a single indirect tax that applies from the manufacturer all the way to the consumer. But here’s the twist: the tax revenue goes to the state where the goods or services are finally consumed, not where they were produced. That’s what makes it a destination-based tax GST system.
Why Did India Need GST?
Before 2017, the Indian tax landscape looked like a buffet of confusing levies:
- Central Excise Duty
- Service Tax
- Value Added Tax (VAT)
- Octroi
- Entry Tax
- Luxury Tax, and more.
This created two major problems:
- Tax-on-tax (Cascading Effect): You paid tax on tax at multiple stages.
- Inter-State Chaos: Different states had different rules, making compliance a nightmare for businesses operating nationwide.
Enter GST in July 2017—a unified tax system designed to simplify everything:
- One tax structure across India.
- Seamless Input Tax Credit (ITC) across the value chain.
- A single compliance framework, instead of juggling central and state laws.
GST Tax Structure in India
Now, here’s where it gets interesting: India didn’t go for a single national GST like some countries. Why? Because of our federal structure, where both the Centre and States have taxation powers. So, GST in India works on a dual model, splitting tax between:
- The Central Government (through CGST and part of IGST).
- The State Governments or Union Territories (through SGST or UTGST, and part of IGST).
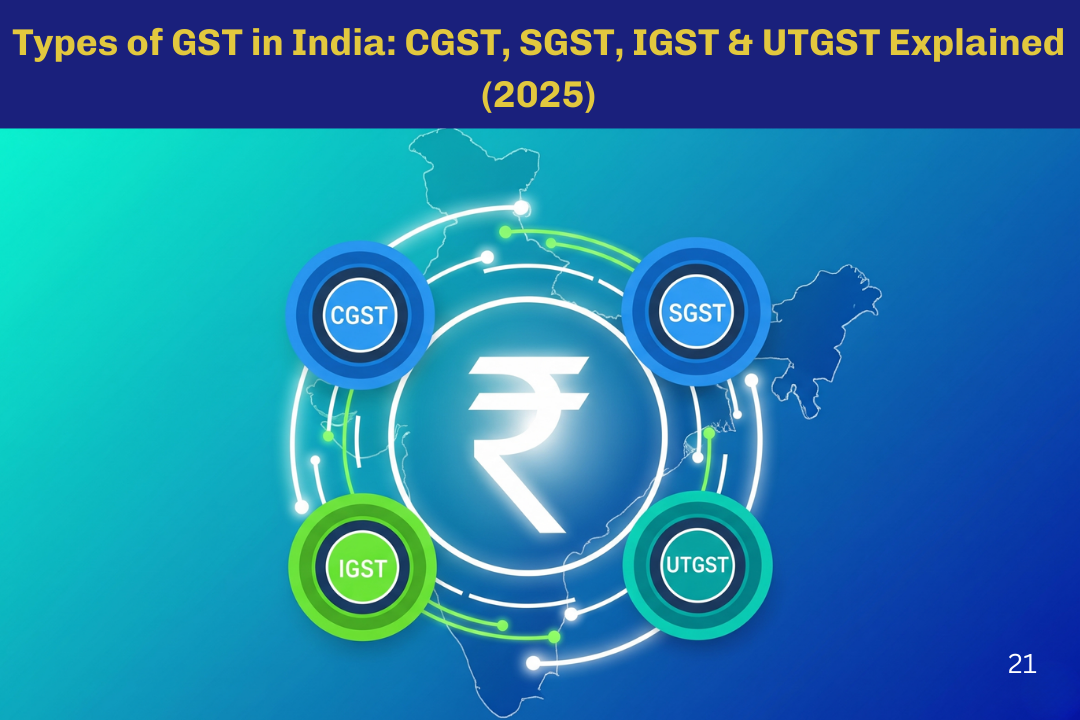
This dual system is why you see multiple components - CGST, SGST, IGST, and UTGST - on invoices.
GST is India’s answer to tax complexity - one nation, one tax (well, almost), and a big step toward a unified market.
Types of GST in India: An Overview
Problem: You see CGST, SGST, IGST (and sometimes UTGST) on invoices and your brain does a small backflip. Which one applies? Why are there multiple taxes when GST was supposed to be “one nation, one tax”? Relax - this section unpacks the four pillars of GST in India in a way you can actually use on Day 1 of filing.
Quick elevator summary (so you don’t get tunnel vision)
Types of GST in India = CGST, SGST, IGST, UTGST.
The deciding factor: Is the supply intra-state or inter-state?
- Intra-state = CGST + SGST (or CGST + UTGST in certain UTs)
- Inter-state / imports / exports = IGST
- GST is destination-based — revenue goes to the state/UT where the goods/services are consumed.
1) Central Goods and Services Tax (CGST) — the Centre’s slice
- Full form: Central Goods and Services Tax.
- When it applies: On intra-state supplies of goods/services — i.e., supplier and recipient are in the same state or UT (that uses SGST).
- Who collects: The Central Government (but the tax is shown separately on invoices).
- How it looks on an invoice: If total GST is 18% on a ₹10,000 sale within the same state, you’d typically show:
- Taxable value: ₹10,000
- CGST (9%): ₹900
- SGST (9%): ₹900
- Total GST: ₹1,800
- Why it matters for businesses: CGST is the central component of input tax credits and matches with CGST liabilities; it cannot be set off directly against SGST liability (IC rules apply - more on that in the ITC section).
2) State Goods and Services Tax (SGST) — the State’s slice
- Full form: State Goods and Services Tax.
- When it applies: Also on intra-state supplies — SGST is the state counterpart to CGST.
- Who collects: The State Government where the supply is made.
- Invoice pairing: Always paired with CGST for intra-state transactions (CGST + SGST).
- Practical note: For bookkeeping you’ll separately record SGST paid and SGST collected; this affects state-level reconciliation and return fields.
3) Integrated Goods and Services Tax (IGST) — for interstate flows & cross-border business
- Full form: Integrated Goods and Services Tax.
- When it applies: On inter-state supplies (seller and buyer in different states/UTs), imports into India, and certain special cases like supplies to/from SEZs (and exports which are generally zero-rated).
- Who collects: Initially collected by the Central Government as IGST.
- Why IGST exists (the core idea): It avoids double taxation and keeps the flow of tax credits clean when goods/services cross state borders. IGST ensures that the consuming state ultimately receives the tax revenue.
- How it appears on an invoice: For a sale of ₹10,000 from Maharashtra to Gujarat with 18% GST:
- Taxable value: ₹10,000
- IGST (18%): ₹1,800
- Settlement mechanics (brief): The Centre collects IGST and then, through the GST settlement mechanism, apportions revenue to the destination state. Input tax credit adjustments during return filing and settlement ensure the tax flow matches consumption location.
- Exports & zero-rating: Exports are typically zero-rated under IGST (i.e., IGST charged = 0, supplier can claim refund of unutilized credits) — important for exporters and international trade.
4) Union Territory Goods and Services Tax (UTGST) — for some UTs without legislature
- Full form: Union Territory Goods and Services Tax.
- When it applies: On intra-UT supplies in Union Territories that do NOT have their own legislature. In such UTs, the tax structure mirrors SGST but the revenue goes to the UT administration.
- Who collects: The Union Territory administration (via the GST system).
- How it pairs: Like SGST, UTGST is shown alongside CGST for intra-UT transactions (CGST + UTGST).
- Practical difference from SGST: Functionally similar — the only practical difference is the destination of revenue (state vs union territory administration).
- Tip: Some UTs that do have legislatures (e.g., Delhi, Puducherry) operate like states for GST purposes and use SGST instead of UTGST.
Intra-state vs Inter-state — the decisive rule (deep dive)
This is the rule every invoicing clerk and CFO must have tattooed somewhere: If supplier and place of supply (where the goods/services are consumed) are in the same state/UT → intra-state; otherwise → inter-state.
Key mechanics to determine place of supply:
- For goods: Usually the location where the goods are delivered (or the place to which they are shipped). If goods are moved by supplier, the place of supply is where the movement ends. If goods aren’t moved (e.g., made available at a showroom), place of supply is where goods are located at time of supply.
- For services: A bit more nuanced — rules include:
- Location of recipient (if registered),
- Location of the supplier if recipient location isn’t available,
- Specific rules for services like restaurant, transportation, events, telecommunication, etc.
- E.g. Consultancy provided remotely: often the place of supply is the location of the recipient (client) if they are registered in India.
- Ecommerce & marketplace sales: Place of supply follows the buyer’s location for goods; for services it depends on nature of service and POS rules. Marketplace operators have specific compliance obligations (GST collection at source in certain cases).
Practical examples (no fluff):
- Intra-state: Seller in Bengaluru sells a laptop to a buyer in Bengaluru. Tax: CGST + SGST.
- Inter-state: Seller in Bengaluru ships that same laptop to a buyer in Chennai. Tax: IGST.
- E-commerce: Seller in Haryana sells via an e-marketplace to a buyer in Bihar — typically IGST unless both buyer and seller are in the same state. Marketplace operator compliance may apply.
- Export: Manufacturer in India ships to a buyer abroad — zero-rated under IGST, with refund/credit mechanisms.
- Union Territory: Supplier in a UT without legislature sells within the same UT — CGST + UTGST.
Why multiple types aren’t just bureaucracy — a quick rationale
- Federal balance: India’s Centre and States both need revenue. Splitting into CGST & SGST (or UTGST) respects that constitutional reality while keeping GST unified in spirit.
- Destination taxation: Because GST is destination-based, the tax must eventually accrue to the consuming state — IGST helps route that revenue correctly across borders.
- Seamless credit: The system is designed so tax paid on inputs can be used to offset tax on outputs across the value chain, even when goods/services move across states (IGST mechanism + set-off rules make this possible).
Quick checklist
- Check supplier location, recipient location, and place of supply before billing.
- For intra-state: charge CGST + SGST / UTGST (as applicable).
- For inter-state: charge IGST.
- For exports: treat as zero-rated IGST, follow documentation and refund rules.
- Keep invoices explicit: show taxable value and each tax component (CGST, SGST/UTGST, IGST) to ease reconciliation and ITC claims.
Deep Dive into Each GST Type
Now that you know the big picture, let’s break down each pillar of GST in India and see how it actually works in the real world.
A. Central Goods and Services Tax (CGST)
What is CGST?
CGST stands for Central Goods and Services Tax, governed by the CGST Act, 2017. This is the tax collected by the Central Government on the supply of goods and services within a state.
Who collects CGST?
The Central Government collects it, and the amount goes straight to the Centre’s revenue account.
When is CGST applicable?
- On intra-state supplies (transactions happening within the same state).
- It’s charged alongside SGST, as both Centre and State share the tax in the dual GST model.
Example with Rate Split:
Let’s say you buy furniture worth ₹1,00,000 in Maharashtra.
- Total GST rate: 18%
- Split: CGST = 9%, SGST = 9%
So, - CGST = ₹9,000 (goes to Centre)
- SGST = ₹9,000 (goes to State)
B. State Goods and Services Tax (SGST)
What is SGST?
SGST stands for State Goods and Services Tax, levied by State Governments under the SGST Act, 2017.
Who collects SGST?
The State Government where the goods or services are consumed.
When is SGST applicable?
- On intra-state supplies, alongside CGST.
- Together, CGST + SGST ensure both Centre and State share the tax revenue fairly.
Example within a state:
Your favorite local restaurant in Karnataka charges you ₹2,000 for a dinner. GST rate is 5%.
- CGST = 2.5% (₹50)
- SGST = 2.5% (₹50)
So your total tax = ₹100, and both Centre and Karnataka Government share the pie.
C. Integrated Goods and Services Tax (IGST)
What is IGST?
IGST stands for Integrated Goods and Services Tax, introduced under the IGST Act, 2017. It’s applicable on inter-state transactions when goods or services move from one state to another or on imports and exports.
Who collects IGST?
The Central Government initially collects IGST and later distributes the share to the consuming state.
Where does IGST apply?
- Maharashtra to Gujarat trade (inter-state).
- Imports (you buy goods from China → IGST applies).
- Exports (zero-rated under GST, but IGST is accounted for in refunds).
Example:
Suppose a trader in Maharashtra sells goods worth ₹1,00,000 to a buyer in Gujarat. GST rate = 18%.
- Entire 18% = IGST (₹18,000)
- Collected by the Centre, then adjusted with Gujarat’s share.
Special Cases:
- GST on imports: IGST applies along with customs duty.
- GST on exports: Zero-rated, meaning tax paid can be claimed back.
D. Union Territory Goods and Services Tax (UTGST)
What is UTGST?
UTGST stands for Union Territory Goods and Services Tax, governed by the UTGST Act. It applies instead of SGST in Union Territories without their own legislature.
Who collects UTGST?
The Union Territory administration, along with the Centre (CGST).
SGST vs UTGST:
- SGST = For States
- UTGST = For Union Territories
Where does UTGST apply?
Union Territories like:
- Andaman & Nicobar Islands
- Chandigarh
- Dadra & Nagar Haveli and Daman & Diu
- Lakshadweep
- Ladakh
Example:
You buy electronics worth ₹50,000 in Chandigarh. GST = 18%.
- CGST = 9% (₹4,500)
- UTGST = 9% (₹4,500)
Difference Between CGST, SGST, IGST & UTGST
Ever wondered, “What’s the real difference between CGST, SGST, IGST, and UTGST?” You’re not alone! Let’s clear the confusion with a quick comparison table and an easy breakdown.
Comparison Table: CGST vs SGST vs IGST vs UTGST
| Aspect | CGST | SGST | IGST | UTGST |
| Full Form | Central Goods and Services Tax | State Goods and Services Tax | Integrated Goods and Services Tax | Union Territory Goods and Services Tax |
| Governing Act | CGST Act, 2017 | SGST Act, 2017 | IGST Act, 2017 | UTGST Act |
| Collected By | Central Government | State Government | Central Government (then shared with States) | Union Territory Administration |
| Applicability | Within a State (Intra-State supply) | Within a State (Intra-State supply) | Between States (Inter-State supply), Imports, Exports | Union Territories without Legislature |
| Example | Furniture sold in Maharashtra | Same furniture sold in Maharashtra | Goods sold from Maharashtra to Gujarat | Electronics sold in Chandigarh |
| Rate Split | Part of total GST with SGST | Part of total GST with CGST | Full GST (no split) | Part of total GST with CGST |
Key Points to Remember
- CGST + SGST apply together on intra-state supplies (e.g., within Karnataka).
- IGST applies on inter-state trade and on imports/exports.
- UTGST replaces SGST in Union Territories without their own legislature (e.g., Chandigarh, Lakshadweep).
Why India Has Multiple GST Types
You keep asking “If GST was supposed to be ‘one nation, one tax’, then why do I still see CGST, SGST, IGST, and UTGST? Isn’t this just reinventing complexity?” Great question. The short answer: politics + federal finance + practical tax engineering. The long answer (below) is where the clarity and the useful decisions for your business live.
India adopted a dual-GST model (CGST + SGST, with IGST for cross-state trade) to honour federal fiscal powers while creating a unified, destination-based tax system that prevents cascading taxes and lets businesses claim seamless input tax credit. In plain English: it balances state revenue needs with the goal of a single market.
The nine reasons (and what they mean for you)
1) Constitutional reality: states must keep revenue power
Why it matters: Under India’s federal system, States have the constitutional right to collect certain taxes. A single central GST would have stripped states of revenue control — politically and economically unacceptable.
Business takeaway: The dual model preserves state autonomy while still simplifying taxation for traders.
2) Destination-based taxation: revenue goes where consumption happens
Concept: GST follows the destination principle taxes accrue to the state/UT where goods/services are consumed, not where they’re produced.
Why split helps: If a product moves cross-state, IGST acts as the instrument to make sure the consuming state ultimately receives its share.
Practical effect: This protects states’ revenue from losing out to out-of-state production hubs.
3) Avoiding the cascading tax problem (tax-on-tax)
Before GST: multiple taxes at different stages caused tax-on-tax (cascading), inflating costs.
With GST split: tax paid on inputs is creditable against output taxes even when goods move across states because IGST is treated conceptually as CGST+SGST in settlement.
Business payoff: Proper invoicing and ITC flow reduces effective tax burden and prevents margin erosion.
4) IGST as a balancing & settlement mechanism
Role of IGST: On inter-state supplies, seller charges IGST (a single line item), paid to the Centre. Later, the Centre apportions the state’s share to the consuming state. IGST is therefore the plumbing that moves money to the right state without making businesses do the math.
Illustration: Seller in Maharashtra sells ₹1,00,000 goods to Gujarat at 18% GST → IGST ₹18,000 collected by Centre. Settlement ensures Gujarat gets the state portion (the equivalent of SGST) and Centre keeps the central portion (CGST).
Why this neat trick was used: It simplifies the invoice (one tax line for inter-state) but preserves destination-based revenue distribution.
5) Political economy — buy-in from states via revenue guarantees & the GST Council
What enabled adoption: States wouldn’t agree to GST without safeguards (e.g., compensation mechanisms originally designed to protect state revenues during transition) and a forum to jointly decide rates and rules — the GST Council.
Business impact: Policy decisions (rates, exemptions) are negotiated with states, so the system has broader legitimacy and stability.
6) Administrative & compliance benefits (central coordination, state execution)
Central role: Central laws and IT backbone (GSTN) provide uniformity.
State role: States administer their share and enforce local compliance.
Result: Standardized returns, harmonized HSN/SAC codes, faster credit matching — but still with state-level specifics (UTGST use, state-level assessments).
7) Trade & market integration: “one market” with state safeguards
Goal: Reduce barriers to interstate trade (uniform rate slabs, single registration concept for many cases) so businesses can operate nationally with fewer tax surprises.
Reality check: Businesses still need strong invoicing and place-of-supply controls to get the benefit.
8) Clearer incentives for exporters / special cases (imports / SEZs)
Exports: Zero-rated — exporters don’t become captive tax-bearers; they can claim refunds or use rebate mechanisms.
Imports: IGST simplifies the tax treatment on imports and ties it into the domestic credit chain.
Why this matters: Keeps Indian goods competitive internationally while protecting state revenue domestically.
9) Tradeoffs & why the split isn’t perfect
Complexities introduced: For multi-state sellers, compliance (multiple registrations, reconciliations) increased compared to a single tax; businesses needed to upgrade ERP/invoicing.
Mitigations: Technology (GSTN, e-invoicing), standardized returns, and clearer place-of-supply rules reduce friction over time.
How GST revenue distribution actually plays out
- Intra-state sale: Tax collected = CGST + SGST (each authority keeps its share immediately).
- Inter-state sale: Tax collected = IGST (Centre collects). Later, the IGST collected is settled between Centre and the destination State so that the consuming state gets the state share and Centre retains the central share — effectively mirroring what would’ve happened if CGST+SGST were charged.
- Net effect: The sum of tax pie is the same; the split just routes it correctly to the consuming state without forcing businesses to calculate dual components in inter-state invoices.
GST compliance for businesses practical implications
- Understand Place of Supply (POS) rules — POS drives whether it’s intra-state (CGST+SGST/UTGST) or inter-state (IGST). Wrong POS = wrong tax.
- Maintain accurate addresses & GSTINs for customers and suppliers — reconciliations depend on this.
- Invoice hygiene: clearly show taxable value, rate, and tax components (CGST/SGST/IGST) so buyers can claim ITC.
- Ledger segregation: keep CGST, SGST, IGST ledgers separate — helps in returns and set-offs.
- ITC reconciliation: match outward invoices (GSTR-1) and incoming credits (GSTR-2B/2A) regularly to avoid blocked credits.
- Multi-state registrations: if you have a physical presence or taxable supplies in multiple states, get GSTINs as required.
- Refunds & exports: follow zero-rating rules and documentation rigorously to avoid delays in refunds.
- E-way bills & transport docs: keep movement evidence — critical for place of supply and audit trails.
- Invest in tech: invoicing software that auto-populates POS and tax type reduces human error massively.
- Train teams: sales & billing staff must know when to charge IGST vs CGST+SGST simple errors cause cashflow headaches.
A short example
- Scenario A (Intra-state): Seller in Delhi sells ₹50,000 worth of goods to buyer in Delhi. GST 18% → CGST 9% (₹4,500) + SGST 9% (₹4,500). Centre and Delhi split revenue immediately.
- Scenario B (Inter-state): Same seller ships to buyer in Mumbai (different state). GST 18% → IGST 18% (₹9,000) collected by Centre. After settlement, Maharashtra receives the equivalent state share; Centre keeps its central share. Buyer in Mumbai can claim ITC as usual.
Why this matters for strategy (not just compliance)
- Pricing decisions: Knowing which tax applies avoids under/overcharging customers and prevents pricing surprises.
- Cashflow planning: Wrong tax application can block ITC and cause working capital stress.
- Expansion plans: Multi-state business models must bake GST compliance into cost forecasts and ERP design.
- Competitive positioning: Efficient GST compliance (fast refunds, clean ITC) can be a cashflow advantage versus slower rivals.
Quick summary
- Why is GST split? To balance a unified tax system with India’s federal structure — protecting state revenues while eliminating cascading taxes.
- GST revenue distribution: Intra-state → CGST to Centre + SGST to State; Inter-state → IGST collected by Centre and apportioned to consuming state.
- For businesses: Proper place-of-supply, clean invoicing, and ITC reconciliation are non-negotiable — they turn the split-GST system from a headache into an operational advantage.
Input Tax Credit (ITC) & Utilization Rules - deep dive
You paid tax on raw materials, logistics and services but when it’s time to file, your books show a pile of ITC and your tax payment screen still wants cash. Or worse: you claimed credit, supplier didn’t pay tax, and now interest + reversals are knocking. Welcome to the world of Input Tax Credit GST is powerful when you use it right, painful when you don’t.
For this you need a clear, actionable map of ITC eligibility, what’s blocked, time limits, the exact order GST will let you set off credits (the infamous ITC utilization rules GST), a worked numeric example that you can copy-paste into training decks, and a compact checklist your billing team can follow.
1) What is Input Tax Credit (ITC) — legal short version
Input Tax Credit (ITC) lets a registered taxpayer reduce their output tax liability by the GST they’ve already paid on inputs (goods or services) used in the course of business. The right to claim ITC, the conditions to claim it, and restrictions are laid out in the CGST Act (Sections 16 & 17) e.g., you must have a valid tax invoice, the supplier must have actually paid the tax to the government (or tax must be paid in the manner permitted), and the goods/services must be used for business purposes.
2) ITC eligibility — the checklist (in plain English)
You can claim ITC only if all of the following are true:
- You are a registered taxpayer.
- You possess a tax invoice / debit note / other prescribed document from a registered supplier.
- You have received the goods or services (rules define when “received” is deemed).
- The tax charged has been paid to the government (either in cash or through permitted utilisation).
- You have furnished your return (as required) for the period.
If any of these fail, the credit is not available or may need reversal with interest.
3) Things you cannot claim (blocked credits) — common traps
Section 17(5) lists categories where ITC is not allowed (short examples): motor vehicles for personal use, certain travel/club/fitness membership costs, food & beverages (with limited exceptions), life/health insurance (except certain cases), and more. These are frequent causes of disallowances during audits—so don’t treat every supplier bill as “ITC-ready.”
4) Time limits & important reversal rules (must-know)
- Time limit to claim ITC: You cannot claim ITC for invoices beyond the due date of furnishing the return for the month of September following the end of the financial year to which the invoice relates (or the date of filing the relevant annual return, whichever is earlier). In short: don’t forget old invoices you can lose credits if you miss the cut-off.
- 180-day payment rule: If a recipient fails to pay the supplier (value + tax) within 180 days of the invoice date (for supplies other than reverse-charge supplies), the recipient must add the ITC claimed back to output tax liability (with interest). If later the recipient pays the supplier, they can reclaim the reversal but interest pain may remain.
5) The exact order ITC is used (the set-off rules) the rulebook (short answer)
The law now requires taxpayers to exhaust IGST ITC first before touching CGST/SGST/UTGST ITC. Once IGST ITC is used for IGST liabilities, any remaining IGST ITC may be used for CGST and/or SGST/UTGST in any order and any proportion. Only after IGST ITC is fully used can CGST/SGST ITC be used as permitted by the remainder of the rules. These rules are in Section 49A/49B and Rule 88A; CBIC circulars explain them and give illustrations. In plain language: IGST first → then CGST/SGST (flexible allocation); but CGST and SGST cannot be set off against each other. (Tax Portal)
Why this exists: it helps the Centre manage IGST balances and speeds settlement between Centre and States, while giving taxpayers some flexibility on how leftover IGST credits are applied.
6) Short, practical set-off algorithm (how your ERP / accountant should apply credits each tax period)
Follow these steps (this is the operational translation of Rule 88A + Section 49A/B):
Step 1 — IGST liability: Use IGST ITC to pay IGST liability first (mandatory).
Step 2 — leftover IGST: If IGST ITC remains, you may apply it to CGST and SGST/UTGST liabilities in any proportion/order. (This is the flexibility Rule 88A provides.)
Step 3 — CGST / SGST after IGST exhausted: Once IGST ITC is fully exhausted, then:
Use CGST ITC to meet CGST liability first; any leftover CGST ITC may then (if needed) be used for IGST liability.
Use SGST ITC to meet SGST liability first; any leftover SGST ITC may then (if needed) be used for IGST liability.
Important restriction: CGST cannot be used to pay SGST and SGST cannot be used to pay CGST. (UTGST follows SGST-like rules for UTs.) (Tax Portal)
7) Illustrative numeric example - copy-paste friendly (shows optimization)
Starting balances (ITC in electronic credit ledger):
- IGST ITC = ₹50,000
- CGST ITC = ₹20,000
- SGST ITC = ₹30,000
This month’s tax liabilities:
- IGST payable = ₹40,000
- CGST payable = ₹25,000
- SGST payable = ₹10,000
How set-off can work (best-practice allocation to avoid cash):
Step A: Exhaust IGST for IGST liability
- Use ₹40,000 of IGST ITC → IGST liability becomes 0.
- Remaining IGST ITC = ₹50,000 − ₹40,000 = ₹10,000.
Step B: Use remaining IGST ITC to reduce CGST/SGST (Rule 88A lets you choose proportion)
- Optimal move here: apply the remaining IGST ₹10,000 to CGST (because CGST liability is larger).
- CGST payable becomes ₹25,000 − ₹10,000 = ₹15,000.
- Remaining IGST ITC = ₹0.
Step C: Use CGST ITC to clear CGST payable
- Use ₹15,000 of CGST ITC (from ₹20,000) → CGST liability becomes 0.
- Remaining CGST ITC = ₹20,000 − ₹15,000 = ₹5,000.
Step D: Use SGST ITC to clear SGST payable
- Use ₹10,000 of SGST ITC (from ₹30,000) → SGST payable becomes 0.
- Remaining SGST ITC = ₹30,000 − ₹10,000 = ₹20,000.
Result: All liabilities (IGST, CGST, SGST) are cleared with no cash payment required, and your leftover credits sit as:
- CGST = ₹5,000 (carry forward), SGST = ₹20,000 (carry forward).
Why this mattered: if you had instead applied the leftover IGST to SGST first, you could have been left with a CGST shortfall that cannot be filled using SGST credit resulting in cash payout. So using leftover IGST smartly minimizes cash outflow. (Two alternative allocations are shown in official circular illustrations.)
8) Cross-utilization of ITC GST — crisp rules you must remember
- IGST ITC → IGST liability first; leftover → CGST & SGST/UTGST in any order. (Rule 88A.) (Tax Portal)
- CGST ITC → CGST liability first; leftover → IGST (if required). Never to SGST.
- SGST ITC → SGST liability first; leftover → IGST (if required). Never to CGST.
This is the formal meaning of “cross utilization of ITC GST” — limited yes, but controlled. Use your ERP to allow only permitted cross-head moves.
9) Common real-world traps (and how to fix them)
- Supplier didn’t pay tax → interest & reversal risk. If supplier fails to deposit GST and your total ledger balance falls below the wrongly-availed credit, interest can be levied on you; CBIC’s circulars clarify how interest is calculated. Reconcile supplier payment reports often. (Goods and Services Tax Council)
- Missing/mismatched invoices → blocked ITC. Use GSTR-2B vs GSTR-1 daily/weekly reconciliation to catch mismatches early.
- Old invoices left unclaimed: watch the September-next-FY deadline — late claims may be refused.
- Using SGST to pay CGST (or vice versa): NOT allowed — and will force cash outflows later. Design your auto-setoff logic around the legal order. (Tax Portal)
- Operational confusion between IGST and inter-state invoicing: ensure POS (place of supply) logic is correct so the right tax head gets credit in the first place.
10) When unutilised ITC can be refunded (exports / inverted duty)
If ITC accumulates because you make zero-rated supplies (exports/SEZ) or due to an inverted duty structure (input tax rate > output tax rate), you can apply for a refund of unutilised ITC under Section 54 (subject to conditions and documentation). Refunds have prescribed procedures (and timelines) — exporters usually claim refunds under Section 54. (Tax Portal, gstdelhizone.gov.in)
11) Quick SOP — what your billing & accounts teams must do weekly
- Reconcile GSTR-2B (ITC statement) with purchase invoices.
- Check supplier returns (GSTR-1) match invoices you’re claiming.
- Monitor IGST balances first; auto-allocate leftover IGST to optimize cashflow (use the numeric logic above).
- Flag invoices older than 10 months (approaching the September-next-FY deadline).
- If a large supplier invoice is unpaid for > 150 days, set a reminder to reverse ITC by day 180 if payment not received.
- Keep a mini-dashboard: IGST balance, CGST balance, SGST balance, monthly liabilities — so setoff decisions can be made proactively.
12) TL;DR & legal sources (so you can paste in a compliance deck)
- Input Tax Credit GST is subject to conditions in Sections 16–19 and limitations under Section 17 (blocked credits).
- ITC utilization rules GST: IGST ITC must be used first; leftover IGST can be applied to CGST/SGST in any order (Rule 88A); CGST/SGST can be used only as permitted thereafter. (Tax Portal)
- Wrong availment / interest and interaction of balances is addressed in CBIC circulars — reconcile daily to avoid reversals and interest. (Goods and Services Tax Council)
- Refunds of unutilised ITC (exports/inverted duty) are available under Section 54 (subject to conditions). (Tax Portal)
Intra-State vs Inter-State Supply: How to Know Which GST Applies
You’re about to raise an invoice and freeze “Do I charge CGST + SGST or IGST?” One wrong click and you block ITC for your buyer, mess up returns, or worse — trigger an audit query. This section gives you a reliable, repeatable rulebook with real cases so you (and your billing clerk) never guess again.
Quick one-liner rule
- If the place of supply is in the same State/UT as the supplier → Intra-state GST (CGST + SGST or CGST + UTGST).
- If the place of supply is in a different State/UT than the supplier → Inter-state GST (IGST).
That short rule is gold - now let’s unpack how to determine the place of supply for different scenarios.
1) Goods the practical mechanics
How to decide: follow the movement and delivery.
- Goods that are moved (shipped)
- Place of supply = location where the movement of goods terminates (i.e., delivery address).
- So: Seller in Bengaluru ships to customer in Chennai → Inter-state → IGST.
- Goods not moved by supplier (collected from seller)
- Place of supply = where goods are located at the time of supply.
- If goods are picked up at supplier’s warehouse in Delhi and buyer takes them away → likely Intra-state if both in Delhi, else IGST if buyer is from another state and picks up from a place in that other state.
- Goods supplied on approval / on trial / consignment
- Generally POS = place where goods are located at time of supply (the consignment location). Movement and invoice timing matter — document everything.
- Important operational tip: Don’t rely on billing address alone. Use delivery/ship-to address (or e-way bill destination) to determine intra/inter status.
2) Services - the general rule and the exceptions (this is where most mistakes happen)
Services split into B2B (registered recipient) and B2C (unregistered recipient) rules — then exceptions.
A. General default rules
- B2B (recipient is a registered GST taxpayer) → Place of supply = location of recipient (so usually Inter-state → IGST if recipient is in different state).
- B2C (recipient NOT registered) → Place of supply = location of supplier (so usually Intra-state → CGST + SGST if supplier and place-of-supply are same state).
B. Key exceptions (must-check list)
For these services, specific POS rules override the B2B/B2C defaults — treat carefully:
- Services related to immovable property (construction, architecture, renting) → POS = location of the immovable property.
- Example: Architect in Mumbai providing service for a Goa property → POS = Goa → IGST if supplier in Mumbai.
- Performance-based services (events, restaurants, concerts) → POS = where service is actually performed.
- Example: Band from Kolkata plays in Pune → POS = Pune → IGST if band’s supplier location is elsewhere.
- Transport of goods (by road/rail) → POS = location where goods are handed over for transportation or place where transport is completed depending on sub-rule — check specifics. Practically treat these as linked to movement in goods rules.
- Supply of services where “location of recipient” is used for telecommunication/digital services etc. (special rules for OIDAR — online info/data access services) — these often follow the recipient location or billing address.
C. Practical tip for services
- Always capture recipient’s GSTIN and registered address for B2B. If the buyer is registered and GSTIN location is a different state → treat as inter-state (IGST) unless an exception applies.
- For B2C services, default to your own state (supplier), unless the service type has a specific POS rule.
3) Special & borderline scenarios (you’ll hit these in real business)
- Exports → treated as zero-rated (IGST mechanics) — typically inter-state logic applies but with export benefits.
- Supply to/from SEZ → special place of supply and refund/zero-rating rules — treat as inter-state for tax mechanics.
- Supply on board a conveyance (ship/aircraft) → POS rules tie to where the conveyance is registered or where the service is provided — check per case.
- Drop-shipping/3PL & warehoused goods → if goods are shipped from a warehouse in State A to buyer in State B, IGST applies even if supplier’s HQ is elsewhere. The physical movement and invoice origin story matter.
4) GST for eCommerce transactions — focused, practical guidance
E-commerce creates two typical headaches: who is the “supplier” and what is the place of supply.
- Goods sold on marketplace (B2C):
- Place of supply for goods = buyer’s delivery location → usually Inter-state → IGST if buyer in different state than where goods are dispatched from.
- Practical: the seller’s dispatch warehouse location vs marketplace hub matters — configure your invoicing/ERP to use ship-to address.
- Services sold online (digital services, SaaS, OIDAR):
- POS often depends on recipient location (for B2B) or supplier (for B2C) plus special rules for digital cross-border supply.
- If selling to an Indian registered business in another state → IGST (B2B rule).
- Marketplace operator role & compliance:
- Marketplaces often have additional compliance obligations (reporting, possible collection at source/TCS) — you must know whether you (seller) or the marketplace is responsible for collection/filing.
- Operationally, reconcile marketplace settlement reports with invoicing and ensure correct tax head (IGST vs CGST+SGST) is used.
- Multi-warehouse sellers:
If you hold inventory in warehouses across states (common for e-commerce), tax treatment depends on which warehouse dispatches the order. Set your OMS/ERP to pick the correct warehouse and auto-determine tax type.
5) Decision checklist (the eight questions billing must ask before issuing invoice)
- Is the supply goods or service?
- Is the recipient a registered GST taxpayer (GSTIN present)? (Yes → B2B rules; No → B2C rules.)
- For goods: where are the goods located at time of supply and where will they be delivered?
- For services: does the service fall under any special POS rules (immovable property, event, transport, telecommunication, digital)?
- What is the GSTIN state code of supplier and recipient? (Compare the first two digits.)
- Does the shipping/delivery address differ from billing address? Use shipping for goods.
- Is this an export / SEZ / e-commerce marketplace supply with special rules?
- Are there multiple warehouses or an agent effecting delivery (drop-ship)? If yes, identify dispatch location.
If any answer points to a different state than the supplier’s principal place of business → IGST; otherwise CGST + SGST/UTGST.
6) Real cases (copy-paste for training) — short, explicit outcomes
- Seller: Delhi (supplier) → Buyer: Delhi → Goods delivered in Delhi → Intra-state → CGST + SGST.
- Seller: Pune → Buyer: Ahmedabad → Goods shipped Pune → Ahmedabad → Inter-state → IGST.
- Web design firm (Bengaluru) → contracts with registered company in Pune (GSTIN: Maharashtra) → Service, B2B → POS = Pune → IGST.
- Music band from Kolkata performs in Goa → Service performed in Goa → POS = Goa → IGST if supplier’s location is different.
- E-commerce seller with warehouse in Haryana sells to buyer in Bihar; order dispatched from Haryana → IGST.
- Local restaurant billing a walk-in customer in Mumbai → Service performed in Mumbai → Intra-state → CGST + SGST.
- Supplier located in Chennai, buyer picks goods up from supplier’s Chennai warehouse but buyer’s GSTIN is in TN → Intra-state → CGST + SGST.
- Manufacturer in Maharashtra sells to an unregistered buyer who picks up goods from manufacturer’s Gujarat branch → POS is where goods were at time of supply (Gujarat) → IGST (since supplier location and POS are different states).
7) Common pitfalls & how to avoid them (practical risk controls)
- Pitfall: Using billing address instead of delivery address for goods → wrong tax charged.
Fix: Invoice micro-checklist: always populate “place of supply” from delivery/ship-to field, not from billing. - Pitfall: Treating all B2B as IGST without checking if service has an exception → wrong tax and blocked credits.
Fix: Add service-type mapping in ERP for immovable/event/transport services. - Pitfall: Marketplace settlements don’t match invoices → reconciliation nightmare.
Fix: Automate reconciliation between marketplace P&L CSV and invoicing; tag each order with warehouse and tax head. - Pitfall: Multiple warehouses lead to wrong dispatch origin → IGST vs CGST errors.
Fix: Use OMS rules to select nearest warehouse and auto-fill POS.
Final thought
Intra-state GST vs Inter-state GST is not a philosophical question it’s a deterministic one if you follow the place of supply rules, shipment origin/destination, and service exceptions. Build simple decision logic into your ERP/OMS, train billing teams with the case set above, and the tax type becomes a checkbox not a guess.
Compliance & Practical Implications for Businesses
So you’ve wrapped your head around CGST, SGST, IGST, UTGST, and maybe even flexed your GST knowledge in a client meeting. But here’s the real question:
How do you stay compliant without turning your life into a tax-time horror story?
Let’s break it down like a pro (without the jargon headache).
Why GST Compliance for Businesses Matters
First, let’s address the elephant in the room:
- Problem: Multiple tax returns, dynamic rules, and tech glitches make GST compliance sound like a boss level you can’t beat.
- Solution: GST is designed to streamline indirect taxation, but you must play by the rules to avoid penalties and cash flow disruptions.
In short, compliance is not optional—it’s your ticket to smooth business operations and ITC benefits.
1. GST Registration – Your Business Passport
Under the GST regime, most businesses with turnover above ₹40 lakh (₹20 lakh for services) need a unified GST registration. This single registration covers:
✔ CGST
✔ SGST/UTGST
✔ IGST
Even if you’re operating in multiple states, you need state-wise registration (yes, GST still likes some complexity).
Example:
- A seller in Mumbai ships goods to Delhi. For this interstate transaction, IGST applies. But the seller still needs Maharashtra GST registration because that’s their operational base.
2. Filing Returns – Not a One-Time Affair
Here’s where it gets real:
- GSTR-1: Monthly details of outward supplies (sales).
- GSTR-3B: Monthly summary return and tax payment.
- Annual Return (GSTR-9): Yearly compliance.
Pro Tip: Missing even one filing can block your Input Tax Credit (ITC), which is like locking away your own money.
3. ITC – The Real Game-Changer
One of the best perks of GST is the Input Tax Credit system. Businesses can claim credit for taxes paid on purchases and offset it against their output tax liability.
Example:
- You pay ₹18,000 GST on raw materials and collect ₹25,000 GST on sales.
- You remit only the difference: ₹7,000, because ITC covers the rest.
But the catch?
- ITC is allowed only if your suppliers have filed their returns. So, choose your vendors wisely!
4. E-Invoicing & Digital Compliance
For businesses with turnover above ₹5 crore, e-invoicing is mandatory. This means generating invoices through the GST portal for real-time validation.
- Reduces fraud.
- Ensures auto-population of returns.
- Sounds techy, but once you set it up, it’s a lifesaver.
5. Penalties for Non-Compliance
Ignore GST rules, and you’re looking at:
- Late fees: ₹50 per day (₹20 for NIL returns).
- Interest: 18% per annum on unpaid tax.
- Blocking of e-way bills & ITC credits.
Bottom line: Compliance costs less than non-compliance.
Key Takeaways for Businesses
- Get registered, stay registered.
- File returns on time—monthly and annually.
- Claim ITC smartly and avoid liquidity crunch.
- Automate compliance if possible—tools like Tally, Zoho Books, or ClearTax are lifesavers.
FAQs – Your GST Questions Answered!
1. What are the different types of GST in India?
India has four types of GST:
- CGST (Central Goods and Services Tax)
- SGST (State Goods and Services Tax)
- IGST (Integrated Goods and Services Tax)
- UTGST (Union Territory Goods and Services Tax)
2. Who collects CGST, SGST, IGST, and UTGST?
- CGST: Collected by the Central Government
- SGST: Collected by the State Government
- IGST: Collected by the Central Government and later distributed between Center & State
UTGST: Collected by the Union Territory administration
3. When does IGST apply instead of CGST and SGST?
IGST applies in inter-state transactions—when goods or services move from one state to another or during import/export.
4. Can input tax credit (ITC) be claimed for all GST types?
Yes, ITC can be claimed for CGST, SGST, IGST, and UTGST, but cross-utilization follows specific rules (e.g., IGST credit is used first).
5. How are CGST and SGST calculated in intra-state sales?
For intra-state supply, GST is split equally:
Example: If GST is 18%, then CGST = 9% and SGST = 9%.
6. How does GST differ in Union Territories vs States?
Instead of SGST, UTGST applies in Union Territories like Delhi, Chandigarh, Andaman & Nicobar Islands, etc.
7. Which GST applies to eCommerce transactions?
- Intra-state sale: CGST + SGST
- Inter-state sale: IGST
Also, eCommerce operators may deduct TCS (Tax Collected at Source) under GST.
8. What is the maximum IGST rate in India?
The maximum IGST rate is 28%, applicable on luxury items like cars and sin goods.
9. Why does India have multiple GST types?
Because India follows a dual GST model to share revenue between Central and State Governments and ensure federal financial balance.
10. Is GST registration mandatory for all businesses?
No, GST registration is mandatory only if your aggregate turnover exceeds ₹40 lakh (₹20 lakh for services) or if you sell across states or via eCommerce.
11. Can a business with multiple states have one GST registration?
No, you need state-wise GST registration for each state where you have a business presence.
12. What happens if a business does not comply with GST?
Non-compliance can lead to:
- Penalties up to ₹10,000
- 18% interest on unpaid tax
Blocking of ITC and e-way bills
13. What is the difference between SGST and UTGST?
SGST applies in states
UTGST applies in Union Territories
Both serve the same purpose: share tax revenue with local governments.
14. Can IGST credit be used to pay CGST or SGST?
Yes. IGST credit is utilized first against IGST liability, then CGST, and then SGST/UTGST.
15. What is the GST for services vs goods?
Most goods and services fall under 5%, 12%, 18%, or 28% slabs, but essential items often have 0% GST.
16. Do freelancers and consultants need GST registration?
Yes, if their turnover exceeds ₹20 lakh (₹10 lakh in special category states) or if they work with clients across states.
17. Are exports subject to GST?
Exports are zero-rated under GST, meaning no GST is charged, and businesses can claim ITC refunds.
18. Does GST apply to imports?
Yes. Imports are treated as inter-state supplies, so IGST applies along with customs duty.
19. How does GST work for online marketplaces like Amazon or Flipkart?
The seller pays GST on sales, and the marketplace deducts TCS (Tax Collected at Source) at 1% before paying the seller.
20. Can GST rates change frequently?
Yes, GST Council revises rates periodically based on industry feedback and revenue needs. Always check the latest GST rate notifications before invoicing.
Contact Us
An expert will call you within 24 hours. No payment required to get started.
 How to Claim a TDS Refund: Step-by-Step Guide
5 minutes read
 DIR-3 KYC Compliance: A Director's Guide to Avoiding Disqualification
5 minutes read
 ITR Filing Last Date September 2026: The Founder's Guide to Tax Audits & Belated Returns
5 minutes read
 Register For ESI & PF Now Or Face Employer Penalties On Every Payroll!
5 minutes read
Have a question about this?
Our team can walk you through what applies to your business and what to do next.
Talk to our teamRelated posts
How should a start-up complete ITR filing
Business entities must file their ITR annually to comply with the tax laws of their respective countries. It helps the government assess and collect the appropriate amount of income tax from taxpayers and ensures proper accountability of financial activities.
. 3 Mins
5 step checklist for GST compliance in Indian Startups
Learn about how GST works. The basics of GST along with its compliances. Uncover what your business needs to keep in mind concerning GST rules and GST compliance.
. 3 min read
₹20 Lakhs and Beyond: Understanding GST for Freelancers in India
Are you a freelancer or aspiring to be one? In this blog, uncover the basics of freelancing and requirements involving GST. Learn about all the exemptions, obligations, and compliances of GST for freelancers in india.
. 5 min readEverything right at your mail.
Request a Call Back
Leave your details and our team will call you.
Chat with us on WhatsApp
Hi there! 👋 Connect with our team on WhatsApp.
Hello FilingBuddy, I would like to know more about your services.
Chat Now